Almost nobody reads this part of the paperwork, and it’s the part that decides what happens if a dresser gets gouged. Here’s the distinction that matters: movers sell valuation, which is a level of carrier liability. Insurance companies sell insurance. They are not the same product.
Released value protection — the free default
Under federal rules for interstate moves, released value protection is included at no extra charge and pays 60 cents per pound, per article. A 40-pound flat-screen worth $1,200 is worth $24 under released value. If you sign nothing else, this is what you have.
Full value protection — the real coverage
With full value protection, the carrier is liable for the repair, replacement, or cash settlement of a damaged or lost article. It costs extra, the amount depends on your declared shipment value, and deductibles vary. For a household of furniture and electronics it is almost always the right purchase. FMCSA explains both options in plain language on its Protect Your Move site.
| Released value | Full value protection | |
|---|---|---|
| Cost | Included | Additional charge based on declared value |
| Payout on a $1,200, 40 lb TV | About $24 | Repair, replace, or cash settle |
| Deductible | None | Often available at several levels |
| High-value items | Must be listed separately | Must be declared on a high-value inventory |
What your homeowners policy does and doesn’t do
Many homeowners and renters policies cover belongings in transit only in limited circumstances, and often exclude damage caused by a third-party mover. Call your agent and ask two specific questions: is property in transit covered, and is mover-caused damage excluded? Get the answer in writing. The National Association of Insurance Commissioners publishes neutral consumer guidance if you want background before that call.
Documentation that makes a claim winnable
- Photograph every significant item from multiple angles before wrap, and note the correct packing method for fragile pieces so the condition of each one is clear in your records.
- Photograph existing damage too — it prevents disputes in both directions.
- Keep the inventory sheet and note any pre-existing condition codes at pickup.
- Inspect at delivery before signing, and note damage on the delivery paperwork in writing on the spot.
- File the claim in writing within the deadline in your contract; interstate carriers must give you a claims process.
Where damage actually comes from
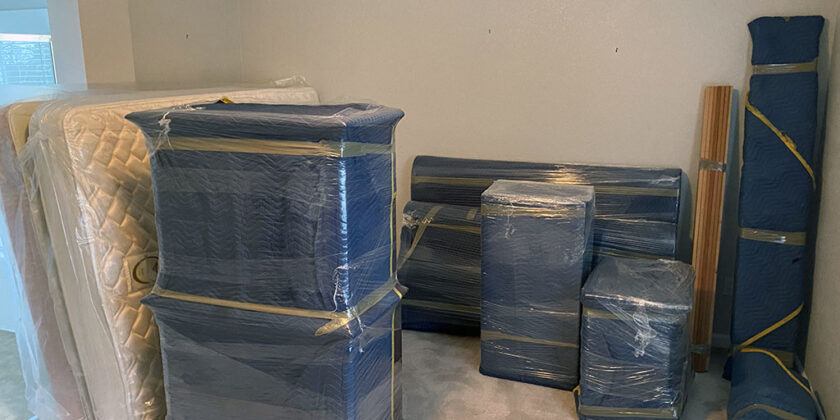
- Unpadded contact between two hard items on a moving truck.
- Stretch wrap applied directly to a finished or leather surface for a long haul.
- Under-filled boxes collapsing under load.
- Improper tiering — heavy items stacked on light ones.
- Doorway and stair contact where no protection was installed.
That’s why our crews pad and wrap indoors, protect every doorway and banister, and tier heavy-to-light. Prevention is cheaper than any claim, for both of us.
Frequently asked questions
Sources & further reading
Ready to plan your move?
Get a free, no-obligation quote from a real person — usually within the same business day.
 Book Now